Statement of cash flows
The statement of cash flows (IAS 7): operating, investing and financing activities, direct and indirect method, why profit is not cash and how GoSoft builds it from cash and bank movements.
A company can make money and still go bankrupt for lack of cash. The statement of cash flows shows where money came from and what it was used for during the period, split into three activities.
- Classify flows into operating, investing and financing.
- Explain the difference between the direct and indirect method.
- Read GoSoft's cash flow statement.
The three activities
| Activity | Inflows | Outflows |
|---|---|---|
| Operating | Collections from customers, interest received | Payments to suppliers, wages, taxes |
| Investing | Sale of fixed assets | Purchase of fixed assets, investments |
| Financing | Loans received, capital contributions | Loan repayments, dividends |
A healthy company generates cash from operations. If operations consume cash for a long time and it is offset with loans, there is a problem even if the income statement shows profit.
Direct and indirect
- Direct method: shows actual receipts and payments by concept. Recommended by IAS 7 and easiest to understand.
- Indirect method: starts from net profit and adjusts it for non-cash items (depreciation) and changes in working capital (receivables, inventory, payables).
Example (indirect method, summarized)
| Item | Amount |
|---|---|
| Net profit | 39,000,000 |
| + Depreciation (not a cash outflow) | 17,000,000 |
| − Increase in receivables (sold but not collected) | (30,000,000) |
| + Decrease in property inventory | 24,000,000 |
| − Decrease in payables (paid debts) | (5,000,000) |
| = Net cash from operations | 45,000,000 |
| Purchase of fixed assets (investing) | (20,000,000) |
| Loan repayments (financing) | (15,000,000) |
| = Net increase in cash | 10,000,000 |
In GoSoft, step by step
Open Financial reports → Cash flows. GoSoft uses the direct method: it takes each cash and bank movement and classifies it by the offsetting account.
Choose units, period and grouping level; click View.
gosoft.app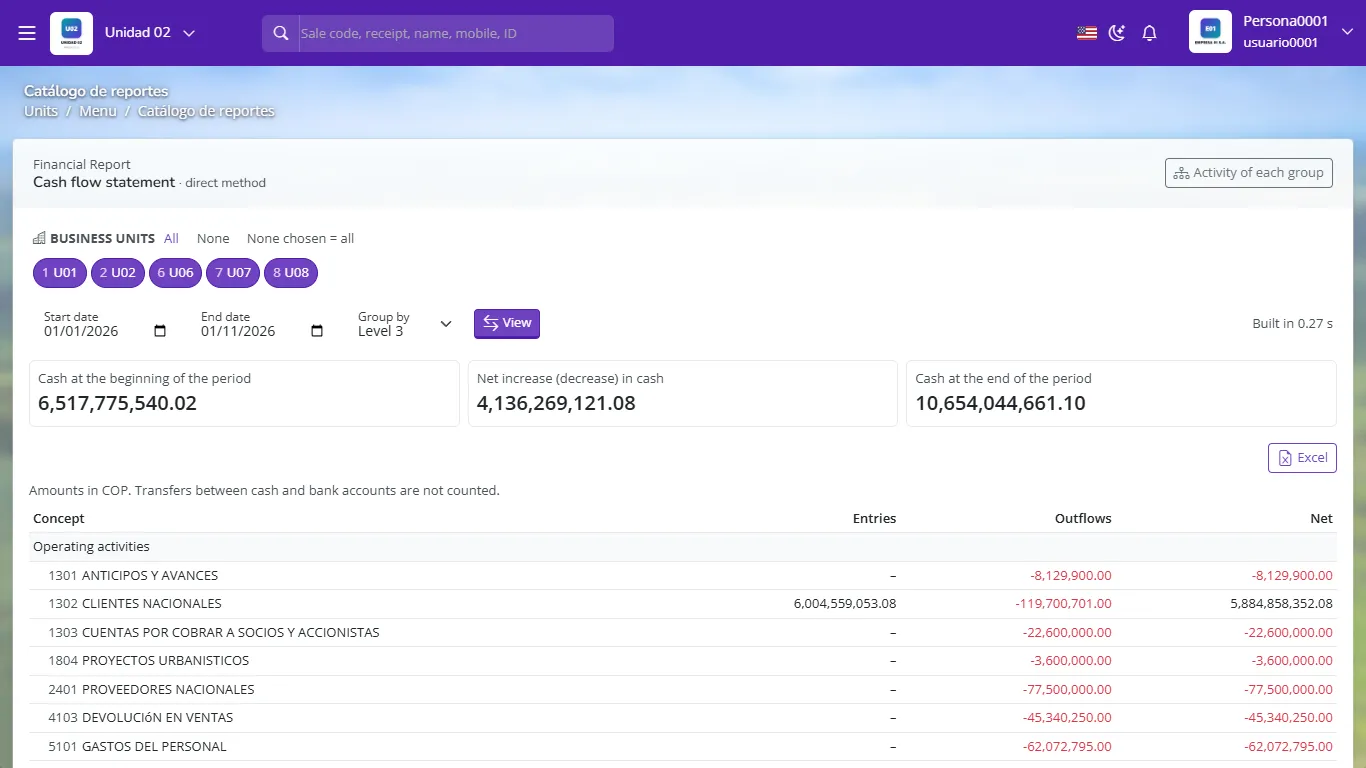
Direct-method cash flow with opening cash, change and closing cash At the top you see opening cash, the net increase or decrease and closing cash. Transfers between cash and banks are not counted, since they are not real inflows or outflows.
With Activity of each group you review or change which activity (operating, investing, financing) each account group falls into.
Closing cash for the period must equal the sum of cash and banks on the balance sheet at the same date.
Which activity does the purchase of a vehicle belong to?
Investing.
Why is depreciation added back in the indirect method?
Because it is an expense that reduced profit but involved no cash outflow.
In which activity does a loan received appear?
Financing.